Best overall for broker-led buying: Alan Boswell Group. Best for a referencing-led route: HomeLet. Best for an agent-managed tenancy: Let Alliance. Best for comparing insurance options: Simply Business. This 2026 shortlist separates buying routes rather than claiming identical cover; Energy Guard supports landlords with property compliance services, not rent guarantee insurance.
- Comparing the best rent guarantee insurance providers landlords can approach starts with policy wording, not the provider name.
- Alan Boswell Group is the shortlist choice for landlords who want a broker-led insurance discussion.
- HomeLet suits a referencing-led enquiry; confirm tenant acceptance before buying rent guarantee cover.
- Let Alliance suits an agent-managed enquiry; Simply Business suits landlords comparing insurance options.
- Energy Guard provides property compliance services, not insurance; certificates and rent protection solve different problems.
Why this matters
Rent guarantee insurance and buildings insurance address different risks. Buildings cover concerns the property; rent guarantee cover concerns insured tenant non-payment, subject to the policy's conditions. A landlord insurance package does not automatically include both.
The practical question is not which provider has the strongest headline. It is whether the policy accepts your tenancy, covers the loss you want protected and gives you a claims process you can follow. A policy that does not accept your tenant is not a useful recommendation.
For a 2026 purchase, compare current documents rather than an old recommendation or a renewal summary. Read the policy wording, schedule and Insurance Product Information Document together. The summary helps you find the important provisions; the wording and schedule determine the cover.
What makes the best rent guarantee insurance provider?
Use these criteria before treating any provider as your default:
- Tenant acceptance: Establish which referencing results, employment circumstances and guarantor arrangements the insurer accepts.
- Rent protection: Check the insured rent limit, payment duration, excess and any period before benefits begin.
- Legal support: Identify whether possession proceedings are included and who controls the legal work.
- Existing arrears: Check how the policy treats missed payments or disputes that started before cover began.
- Claims duties: Find the reporting deadline, evidence requirements and restrictions on taking action independently.
- Document readiness: Confirm which tenancy, deposit, referencing and compliance records the insurer requires.
Ask each provider to answer the same questions against the same property and tenancy. Otherwise, you are comparing different risks disguised as competing offers. Keep written answers with the documents you receive, particularly where your circumstances do not fit a straightforward employed-tenant application.
Do not select a policy because the application is short. Ease of purchase and suitability at claim stage are separate questions.
Rent guarantee insurance providers at a glance
These rankings identify the most useful enquiry route for each landlord. They do not rank claims performance or promise that a particular application will be accepted.
| Provider | Best for | Standout buying route | Key limitation to resolve |
|---|---|---|---|
| Alan Boswell Group | Broker-led buying | Discussing insurance requirements with a broker | Confirm the actual insurer, wording and claims responsibilities |
| HomeLet | Referencing-led enquiries | Starting with a tenant-referencing specialist | Confirm whether your existing references meet the policy requirements |
| Let Alliance | Agent-managed tenancies | Starting through a lettings-focused business | Establish whether the landlord or agent arranges and administers cover |
| Simply Business | Comparing insurance options | Using an insurance comparison and broking route | Do not assume every landlord policy includes rent guarantee |
No provider wins solely because its name appears on a shortlist. The right choice is the provider that supplies an acceptable policy for your tenancy and explains the obligations clearly.
1. Alan Boswell Group: best for broker-led buying
Alan Boswell Group is an insurance broker. Start here when you want to discuss rent protection alongside your other landlord insurance requirements rather than choose from a headline alone. Ask the broker to distinguish its role from the insurer's role before you proceed.
For your 2026 enquiry, describe the tenancy as it exists, including any arrears, guarantor and previous dispute. Request the wording for the proposed policy and identify the organisation that handles claims. Advice about selecting cover is not the same service as administering a claim.
Alan Boswell Group pros:
- A broker-led route gives you a place to discuss the risk before selecting cover.
- You can frame the enquiry around your tenancy rather than a generic property description.
- You can ask how rent protection fits with your wider insurance arrangements.
Alan Boswell Group cons:
- The broker's name does not establish the terms of the underlying policy.
- You must distinguish the broker, insurer and claims administrator.
- A discussion does not replace written confirmation of tenant eligibility.
Best for: Landlords who want a broker-led conversation and clear identification of the policy they are buying.
Verdict: Buy only after the proposed wording matches your tenancy and protection needs.
2. HomeLet: best for a referencing-led enquiry
HomeLet operates in tenant referencing and landlord insurance. It is a relevant starting point when your rent guarantee enquiry begins with checking a prospective tenant. Keep the referencing decision and the insurance acceptance decision separate until the provider confirms their relationship.
Ask whether references already obtained elsewhere are acceptable, and what happens if a guarantor is required. If you are insuring an existing tenancy, explain that explicitly. Do not assume a service designed around the start of a tenancy applies unchanged after the tenant has moved in.
HomeLet pros:
- Its referencing focus makes tenant acceptance a natural starting question.
- You can discuss the relationship between the reference outcome and the insurance application.
- It provides a relevant enquiry route when you are preparing a new tenancy.
HomeLet cons:
- A completed reference does not itself prove insurance eligibility.
- You need to check how existing references and guarantors are treated.
- An existing tenancy needs its own acceptance check.
Best for: Landlords who want to resolve referencing requirements before committing to rent protection.
Verdict: Buy only once the tenant's reference outcome meets the proposed policy's acceptance rules.
3. Let Alliance: best for an agent-managed tenancy
Let Alliance is a lettings-focused business offering referencing and insurance services. It belongs on your shortlist when an agent is involved in arranging the tenancy or discussing rent protection. Start by establishing who holds the policy and who must act when rent is missed.
Agent involvement does not remove your need to understand the cover. Request the relevant documents and agree who reports arrears, supplies evidence and communicates with the claims handler. Put those responsibilities in writing so that the landlord and agent do not each assume the other has acted.
Let Alliance pros:
- A lettings-focused route fits an enquiry involving a managing agent.
- Referencing and insurance requirements can be discussed in the tenancy-management context.
- The enquiry creates an opportunity to clarify responsibility for reporting arrears.
Let Alliance cons:
- You must establish whether the landlord or agent is the policyholder.
- An agent's description of protection is not a substitute for the wording.
- Unclear reporting responsibilities leave an avoidable administrative gap.
Best for: Landlords whose managing agent is involved in selecting or administering rent protection.
Verdict: Hold until policy ownership and claims responsibilities are documented.
4. Simply Business: best for comparing insurance options
Simply Business provides an insurance comparison and broking route. It suits landlords who want to compare insurance options rather than begin with a referencing service or managing agent. Make rent guarantee an explicit requirement instead of assuming it forms part of every landlord insurance result.
For a 2026 comparison, separate buildings cover, liability cover, legal expenses and rent guarantee. These labels describe different protections. Then compare the rent guarantee wording itself, including eligibility, benefit limits and claims duties, rather than comparing package names.
Simply Business pros:
- A comparison route supports reviewing more than one insurance option.
- You can make rent protection a specific requirement in your enquiry.
- It gives you a structured starting point for separating different landlord cover types.
Simply Business cons:
- A landlord insurance result is not proof that rent guarantee is included.
- Comparison summaries do not contain every exclusion or condition.
- You still need to identify the insurer and read the proposed wording.
Best for: Landlords who want to compare insurance options and are prepared to check each proposal in detail.
Verdict: Buy only after confirming rent guarantee is included and suitable, not merely mentioned.
How these providers are ranked
The order follows buying needs: broker discussion, tenant referencing, agent involvement and comparison. Those distinctions explain where to start; they do not establish that one insurer pays claims better than another.
The criteria remain the same across all four routes. Tenant acceptance comes first, followed by the actual rent benefit, legal support and duties during a claim. Treat this as an enquiry shortlist, not a substitute for policy selection.
Check the tenancy before choosing cover
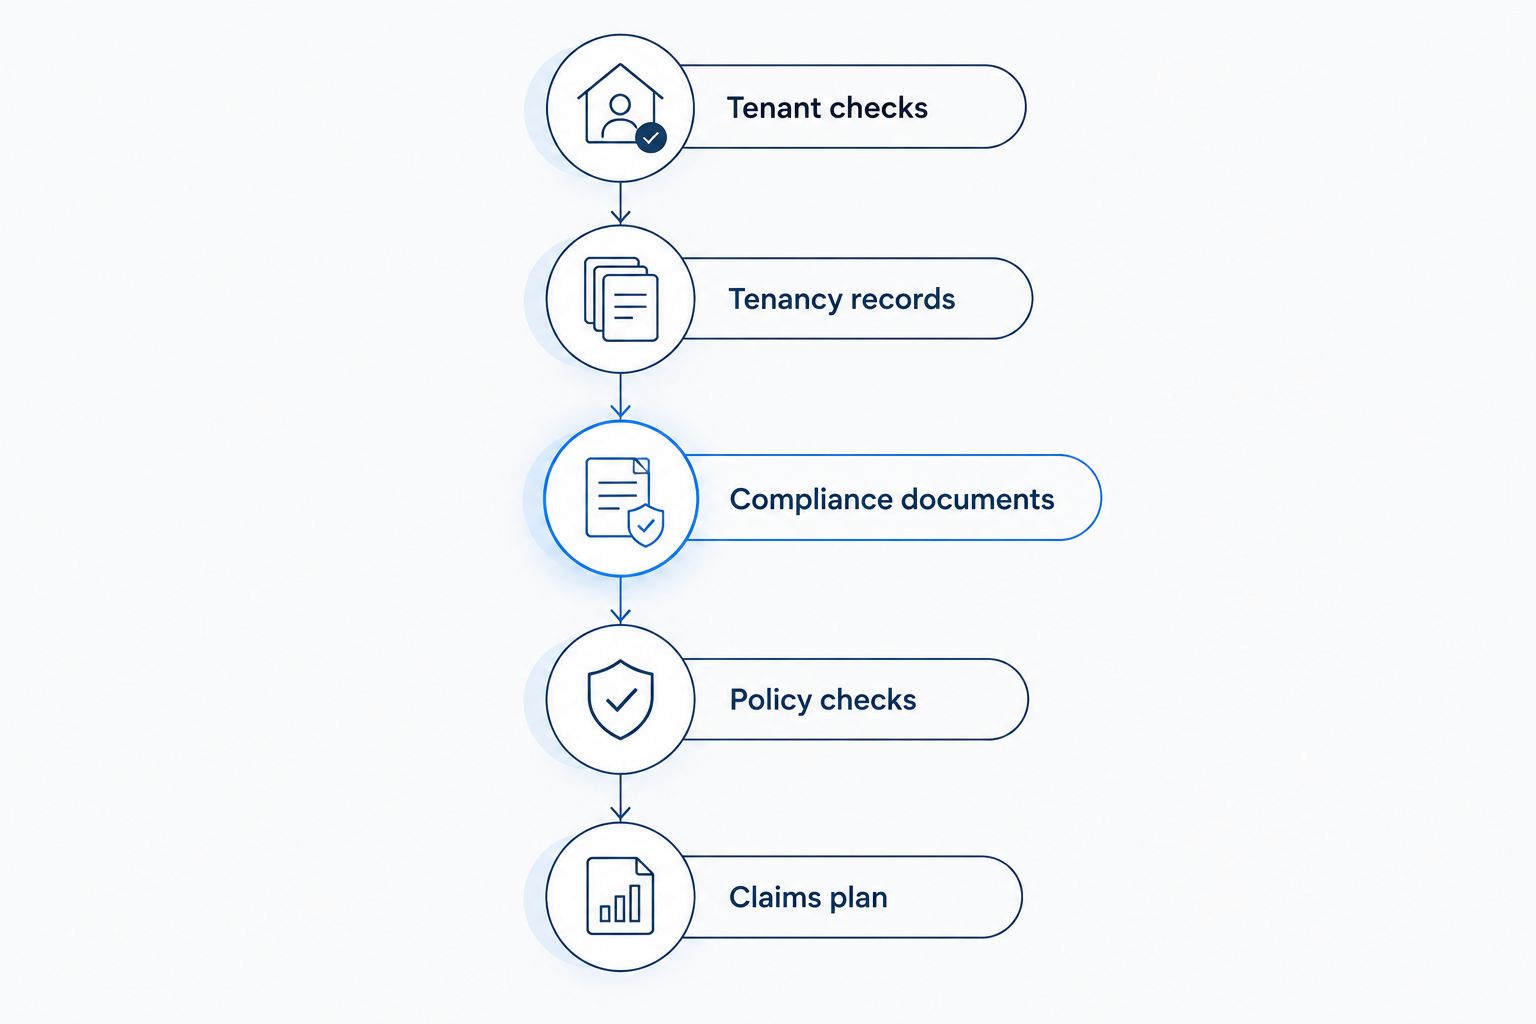
Use this sequence before submitting an application or asking an agent to arrange protection. It keeps eligibility questions ahead of the buying decision.
Tenant checks
Collect the references and guarantor information you intend to rely on. Ask whether they satisfy the proposed policy, including any requirements about who performed the checks. Disclose circumstances that affect acceptance rather than expecting the insurer to infer them.
Tenancy records
Keep the signed agreement, rent schedule and deposit records together. Check that the property address, tenant names and contractual rent match the insurance application. Resolve discrepancies before buying, not after a missed payment.
Compliance documents
For properties with relevant gas installations, landlord gas safety checks are generally required every 12 months. Read the guide to gas safety certificate companies in London when planning that part of your compliance file.
For covered private rented tenancies in England, electrical inspection and testing is required at intervals of no more than 5 years, or sooner where the report specifies. An EPC is generally valid for 10 years. These are separate requirements; one certificate does not replace another.
Energy Guard provides EPC certificates, gas safety checks and EICR services across London and Greater London. Energy Guard is a property compliance service provider for landlords and estate agents, not a rent guarantee insurer.
Policy checks
Ask the provider which documents are conditions of cover and which are needed during a claim. Do not assume that meeting a legal requirement automatically satisfies every insurance condition. Retain the version of the wording supplied for your 2026 purchase.
Claims plan
Record where to report a missed payment and who will do it. If an agent manages the property, agree how the agent will alert you and preserve the rent account. Follow the policy's instructions before instructing separate legal action.
Which rent guarantee insurance provider should you choose?
Start with Alan Boswell Group if you want a broker-led discussion. Choose HomeLet as your first enquiry when referencing is the unresolved issue, Let Alliance when your agent is involved, and Simply Business when comparison is your preferred route.
Before accepting any 2026 proposal, ask for written answers to these questions:
- Does this policy accept this tenant and tenancy?
- What rent loss does it cover, and where does payment stop?
- What must I report, provide or avoid doing during a claim?
If those answers are unclear, hold the purchase. Changing the provider name does not solve an unresolved eligibility problem.
FAQ
What's the best rent guarantee insurance provider for landlords?
The best provider is the one whose policy accepts your tenancy and covers the rent-loss risk you need protected. Alan Boswell Group is a starting point for broker-led buying; HomeLet, Let Alliance and Simply Business suit different enquiry routes.
Is rent guarantee insurance included in landlord insurance?
Rent guarantee insurance is not automatically included in landlord insurance. Check the schedule and wording for an explicit rent guarantee benefit rather than relying on the package name.
Is HomeLet better than an insurance broker?
HomeLet and an insurance broker offer different starting points, so neither is automatically better. A referencing-led enquiry suits landlords resolving tenant acceptance; a broker-led enquiry suits landlords discussing insurance requirements.
Can I get rent guarantee insurance for an existing tenant?
Acceptance for an existing tenant depends on the proposed policy. Tell the provider when the tenancy began, supply the existing references and disclose any arrears or dispute before applying.
Does rent guarantee insurance cover rent already owed?
Do not assume a new policy covers existing arrears. Disclose missed payments and ask for written confirmation of how the proposed policy treats losses or disputes that began before cover.
Do I still need gas safety and electrical certificates?
Yes, insurance does not replace applicable property compliance duties. Keep the required certificates and inspection records, then check whether the insurance policy imposes additional document conditions.
Can Energy Guard arrange rent guarantee insurance?
Energy Guard's stated services are property compliance certificates, energy assessments, PAT testing and floor plans. Use an insurance provider or broker for rent guarantee enquiries and keep compliance documentation as a separate task.
One last thing
Write down who must report the first missed payment before you need to claim. A policy can be clear while the arrangement between landlord and agent is not. Put the reporting contact, document location and responsible person in the same file as the policy wording.